Jim: sell & get paid instantly

Screenshots
Details
- Rating
- 471.00 reviews
- Version
- 1.4.19
- Developer
- CloudWalk
Analysis by Norviv
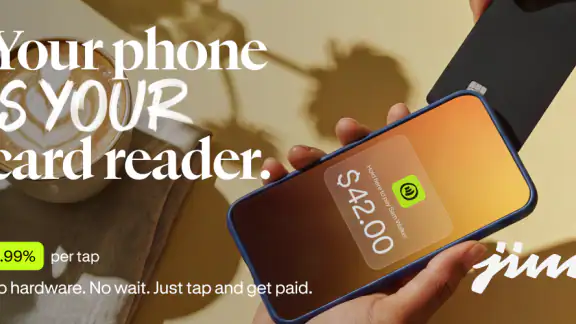
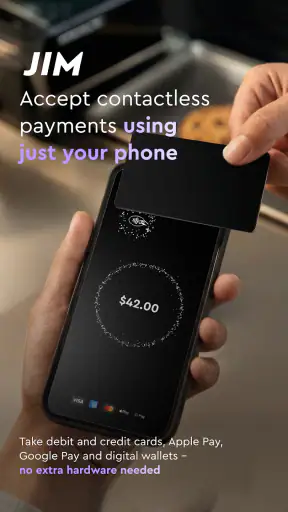
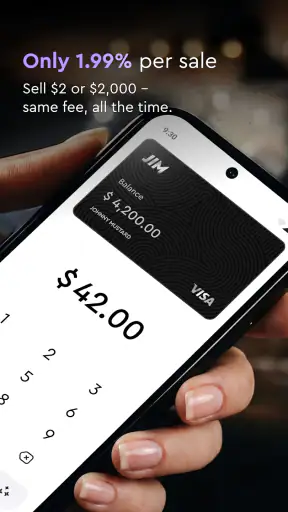
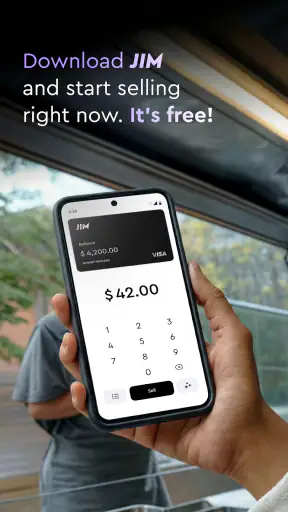
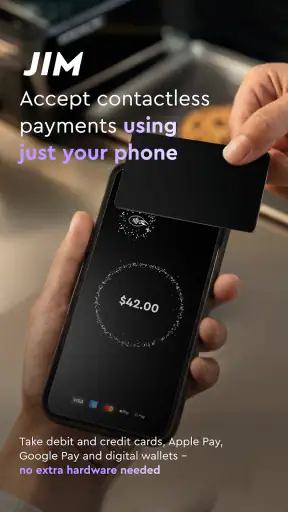
Jim is a finance app from CloudWalk that turns a compatible phone into a practical way to accept card payments. I approached it as a first-time seller would: install it, understand what the app is trying to do, and decide whether it could replace a separate card reader for occasional or mobile sales. The idea is appealing because it keeps the payment tool close at hand, but the real value depends on how comfortably your customers can pay and how well the app fits your existing business routine.
At no cost to download, Jim is aimed at people who need a simple point-of-sale option rather than a full accounting system. Its store summary focuses on selling from anywhere and receiving payment quickly, which makes sense for market stalls, independent services, small shops, and informal selling situations. I would not treat it as a complete business-management platform. Its strongest role is narrower and more useful: making the phone itself part of the checkout process.
What using Jim feels like for a first-time seller
The first thing I noticed about this kind of app is that convenience is not just about speed. A phone-based card reader removes one piece of equipment from the day, but it also makes the phone, its battery, its connection, and its screen part of the payment experience. That trade-off matters. If you already carry your phone everywhere, Jim can feel much lighter than carrying a separate terminal. If your phone is old, nearly out of battery, or needed for other work, the same arrangement can become a source of stress.
Jim is listed as free and suitable for Everyone, so it is approachable for a broad audience. The app has an average rating of 4.4 from around 2.2 thousand ratings, with more than 100 thousand installs. Those figures suggest that it has attracted meaningful interest without making it a universal replacement for every payment setup. I read that as a reason to try it in a controlled situation first, not as a reason to move every transaction to it immediately.
CloudWalk’s product is especially relevant to sellers who work away from a fixed counter. Imagine a personal trainer finishing a session, a craft seller taking an order at a local event, or a repair professional collecting payment after completing a visit. In each case, the useful question is not whether the app sounds modern; it is whether the customer can complete the payment without confusion while you keep the interaction moving.
Compared with cash, Jim can reduce the need to carry change and can make a purchase easier for customers who do not have notes with them. Compared with a traditional card terminal, it may reduce the amount of hardware you need to bring. Compared with a bank transfer, a card-based checkout can feel more familiar to a customer who expects to tap or use a card. The compromise is that Jim is tied more closely to the phone and the app’s supported payment flow than those alternatives are.
Setting up without rushing the first sale
I recommend installing Jim before you are standing in front of a customer. The app is currently at version 1.4.19 and requires Android 7.0 or later, so the first practical check is whether your phone meets that requirement and has enough working battery for a selling session. The installation itself is only the beginning. A calm setup gives you time to understand the screens, sign-in steps, and payment prompts before money is involved.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
After opening it, I would keep the first session deliberately simple. Look for the path that begins a sale, identify where the amount is entered, and read each confirmation screen rather than tapping through quickly. If the app asks you to complete account or seller details, use information you can verify easily and keep your business details consistent. Payment tools are a poor place for guesswork, especially when a small typing error can slow down a customer later.
One useful habit is to prepare a short list of your most common prices before using Jim in public. You do not need an elaborate catalog to benefit from this. Even a handwritten note beside you can prevent the awkward pause of calculating a total while a customer waits. For variable jobs, decide in advance whether you will enter one final amount or build the total during the conversation. A phone payment app works best when the price has already been agreed clearly.
Another practical step is to choose the phone position carefully. The customer needs to see what is happening, and you need to keep control of the device. I would avoid placing the phone flat on a crowded table where it can be covered by products, receipts, or bags. A clear screen and a short explanation make the process feel more trustworthy than silently passing the phone back and forth.
Because Jim is a payment tool rather than a replacement for every business record, I would also decide how you will note each completed sale. A simple daily log, invoice process, or existing bookkeeping method can sit alongside it. This is one of the less obvious trade-offs: accepting payment and organizing the business around that payment are separate jobs. Jim may make the first job easier, but it does not remove the need for the second.
Making the first meaningful payment
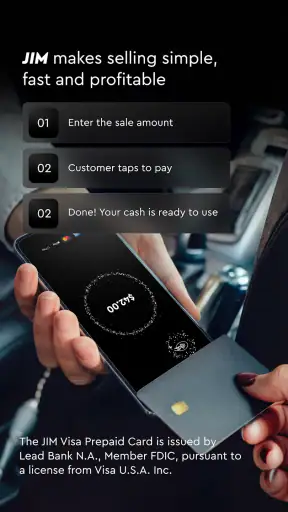
For a first real test, I would choose a low-pressure sale with a product or service whose price is already known. Enter the amount slowly, show the customer the total, and explain what they should do next in plain language. Then wait for the app to show that the transaction has reached its completed state before treating the sale as finished. This simple pause is important because a customer’s attempt to pay is not the same thing as a confirmed payment.
A realistic example would be a weekend seller offering a small handmade item at a community event. The seller can keep the stock and phone together, enter the agreed price when someone chooses an item, and complete the checkout without returning to a fixed booth. The benefit is not only speed. It also means the seller can move around and meet customers where they are. The weakness appears if the phone loses connection, runs low on power, or becomes difficult to use in bright outdoor conditions.
I would test the complete routine before relying on it: start a sale, let the customer follow the payment prompt, wait for confirmation, and then record the transaction. Do not stop at opening the payment screen. The moment that teaches you the most is the end of the process, when you need to know what you will show the customer and what you will do with your own record afterward.
It is also worth practicing how you will handle a customer who asks whether the payment worked. Keep your answer tied to the confirmation shown in the app rather than relying on a sound, vibration, or the customer’s bank notification. If the screen is unclear, take a moment to check it instead of starting a second payment immediately. Duplicate attempts are an avoidable risk with any digital checkout, and calm verification is more useful than speed for its own sake.
The best first-use rule is simple: treat the confirmation screen as the finish line, not the customer’s first tap. That habit makes Jim safer to use and helps you build a repeatable checkout routine before sales become busy.
Where new users may hesitate
The phrase “get paid instantly” can create an expectation that every part of the transaction will feel instant. In practice, the seller still needs to enter the right amount, guide the customer, wait for the result, and keep a record. The app can shorten the equipment side of the process, but it cannot remove those human steps. I would explain this to anyone using Jim for the first time so the promise of speed does not turn into rushed handling.
Another common confusion is assuming that a phone automatically behaves exactly like a dedicated card terminal. A phone-based experience can be more convenient, but it is also more dependent on the particular device and the conditions around you. A busy outdoor event, a crowded network, or a phone being used for calls and messages can make the workflow feel less smooth than it did during a quiet test.
This is why I would not make Jim the only payment option on the first day. Keep a backup that suits your business, whether that means cash, a familiar transfer method, or another established checkout route. A backup is particularly sensible for sellers who work in places where reception is unpredictable or who cannot afford to pause a customer line while troubleshooting a phone.
People also sometimes confuse a free app with a free payment service in every possible sense. Jim is free to download, but a seller should still read the current terms shown during account setup and payment use before making business decisions. I would never price products or promise a particular margin until I had understood the costs and settlement details that apply to my own situation. That is not a criticism of Jim; it is a necessary discipline with any financial app.
Privacy and device security deserve ordinary, practical attention too. I would use a screen lock, keep the phone updated, and avoid handing the unlocked device to a customer without watching the interaction. A payment phone contains more than the payment app, so protecting the device protects other personal and business information as well. These steps are easy to overlook when the main attraction is convenience.
Who benefits most from this approach
Jim makes the most sense for a small seller who values mobility and does not want to carry a separate reader for every occasional transaction. It can be a good fit for independent workers, pop-up sellers, service providers, and people testing a small business idea. The phone-based format is also useful when the selling location changes throughout the day and a fixed checkout counter would be impractical.
I would be more cautious if your business serves a constant queue, needs several employees to take payments, or depends on a large amount of stock and customer information being managed at the register. In those situations, a dedicated terminal or a broader point-of-sale system may be better because the payment device is only one part of a larger operation. Jim’s appeal is its directness, not its ability to replace every specialized business tool.
It may also be the wrong choice for someone who wants a payment setup completely separate from their personal phone. If you use one device for work, navigation, communication, and personal tasks, payment interruptions can affect the rest of your day. A separate terminal costs more equipment-wise, but that separation can be valuable for privacy, reliability, and staff handover.
For a customer, the experience can be pleasantly straightforward when the seller knows the routine. For the seller, the main learning curve is not the idea of accepting a card; it is managing the small details around the transaction. Amount accuracy, confirmation, battery planning, and record keeping are what distinguish a smooth Jim session from an improvised one.
How it compares with familiar alternatives
Cash remains the simplest option when there is no dependable connection and the seller is comfortable handling change. Jim has an advantage when customers prefer cards and the seller wants less physical money to manage. The choice becomes less clear for very small purchases, where entering an amount on a phone may take longer than accepting a coin or note from a prepared customer.
A bank transfer can be convenient between people who already trust each other, but it can also require the seller to check names, references, and payment status manually. Jim is more suitable when you want a defined checkout interaction rather than asking a customer to type banking details. I would still keep the two methods conceptually separate: one is a payment app workflow, while the other is a transfer arrangement with its own verification habits.
A dedicated card reader is the stronger alternative when reliability, shared use, and a familiar countertop experience matter more than carrying less hardware. Jim wins on portability and the possibility of using the phone already in your pocket. The reader wins when you want the payment device to remain available while your phone handles other tasks. Neither is automatically better; the right answer depends on whether mobility or operational separation is your bigger problem.
Traditional point-of-sale software is usually the better choice for a growing shop that needs detailed inventory, staff permissions, printed receipts, or deeper reporting. Jim can be a sensible starting point for someone who mainly needs to accept payments, but I would not choose it solely because a larger system feels intimidating. If your daily pain is stock control rather than payment acceptance, the broader system may save more time even if it requires more setup.
Building a dependable routine after the first sale
Once the first payment works, my next step would be to create a repeatable opening and closing routine. Before selling, check the phone’s charge, open Jim, and make sure you know the prices or totals you expect to enter. After selling, review your completed transactions and transfer the information into whatever record you use for the business. This takes only a little discipline, but it prevents the app from becoming a disconnected collection of payments.
For changing prices, say the total out loud before entering it. That small confirmation catches mistakes that a hurried thumb can miss. For services, write down the customer’s agreed work separately from the payment amount. This helps when the same client returns or asks about the job later, because the payment record alone may not explain what was purchased.
I would also keep the app updated when practical, while avoiding a major change immediately before an important selling event. The current version is 1.4.19, and version information is useful when you need to describe your setup or seek help. More importantly, test the exact phone and selling environment you plan to use; an app that works well at home still needs to prove itself at the place where customers will actually pay.
My overall view is that Jim is a focused, approachable option for turning a phone into part of a mobile checkout. CloudWalk has positioned it for sellers who want to accept card payments without carrying a separate reader, and that can be genuinely useful in everyday situations. I like the idea most for occasional sellers and independent workers who are willing to plan around battery, connectivity, confirmation, and record keeping.
I would skip it as my sole payment solution if my business required a full register, several operators, or a guaranteed dedicated device throughout the day. For everyone else, the sensible path is to install it, complete the setup away from customers, run one small test sale, and keep a backup until the routine feels natural. Jim is free, rated for Everyone, and available for Android users on version 7.0 or later, but its real success comes from matching that simple tool to a realistic selling workflow.
Frequently Asked Questions
01What is Jim: sell & get paid instantly?
Jim: sell & get paid instantly is a marketplace app designed to make selling unwanted items faster and more convenient. You can create listings from your phone, add photos and descriptions, communicate with interested buyers, and manage offers in one place. Its main appeal is helping sellers complete transactions quickly rather than waiting through a lengthy traditional selling process.
02How does selling an item through Jim work?
After installing the app, you generally create a listing by uploading clear photos, entering the item’s title and condition, adding relevant details, and setting a price. Once published, potential buyers can view the listing and contact you or make an offer, depending on the available features. Before accepting anything, check the buyer details, meeting arrangements, and payment information carefully.
03Do I really get paid instantly when I sell something?
The phrase “get paid instantly” describes the app’s fast-payment focus, but the exact timing can depend on the transaction method, buyer confirmation, account verification, and payment provider. Some payments may appear immediately, while others can require processing time. Always confirm that money has actually arrived in your account before handing over an item, and never rely only on screenshots or payment promises.
04Is Jim safe to use for buying and selling?
Jim can simplify local or online transactions, but marketplace safety still depends on your own decisions. Avoid sharing unnecessary personal information, keep conversations inside the app when possible, and be cautious of buyers or sellers who pressure you to act quickly. For in-person exchanges, choose a public location and consider bringing someone with you. Watch for counterfeit payment notices, suspicious links, and requests to pay outside the app.
05What should I know before downloading and using Jim?
Before downloading Jim, review the current app-store description, supported countries, age requirements, privacy policy, and available payment options, since marketplace features may vary by region. You may need to create an account and provide contact or verification details. Also consider delivery arrangements, platform fees, refund rules, and dispute procedures. Reading these conditions first can help you understand the real cost and responsibilities involved.


